In many organisations, the bank guarantee falls into the category of subjects without a clear single owner. The lawyer drafts the wording, finance liaises with the bank to have it issued, and the project team sends it to the other party. This lack of ownership is sometimes a source of tension, but also of oversights that penalise projects. In fact, a guarantee is not a legal document: it is a project financing tool, found on almost all operations of a certain size, public and private alike.
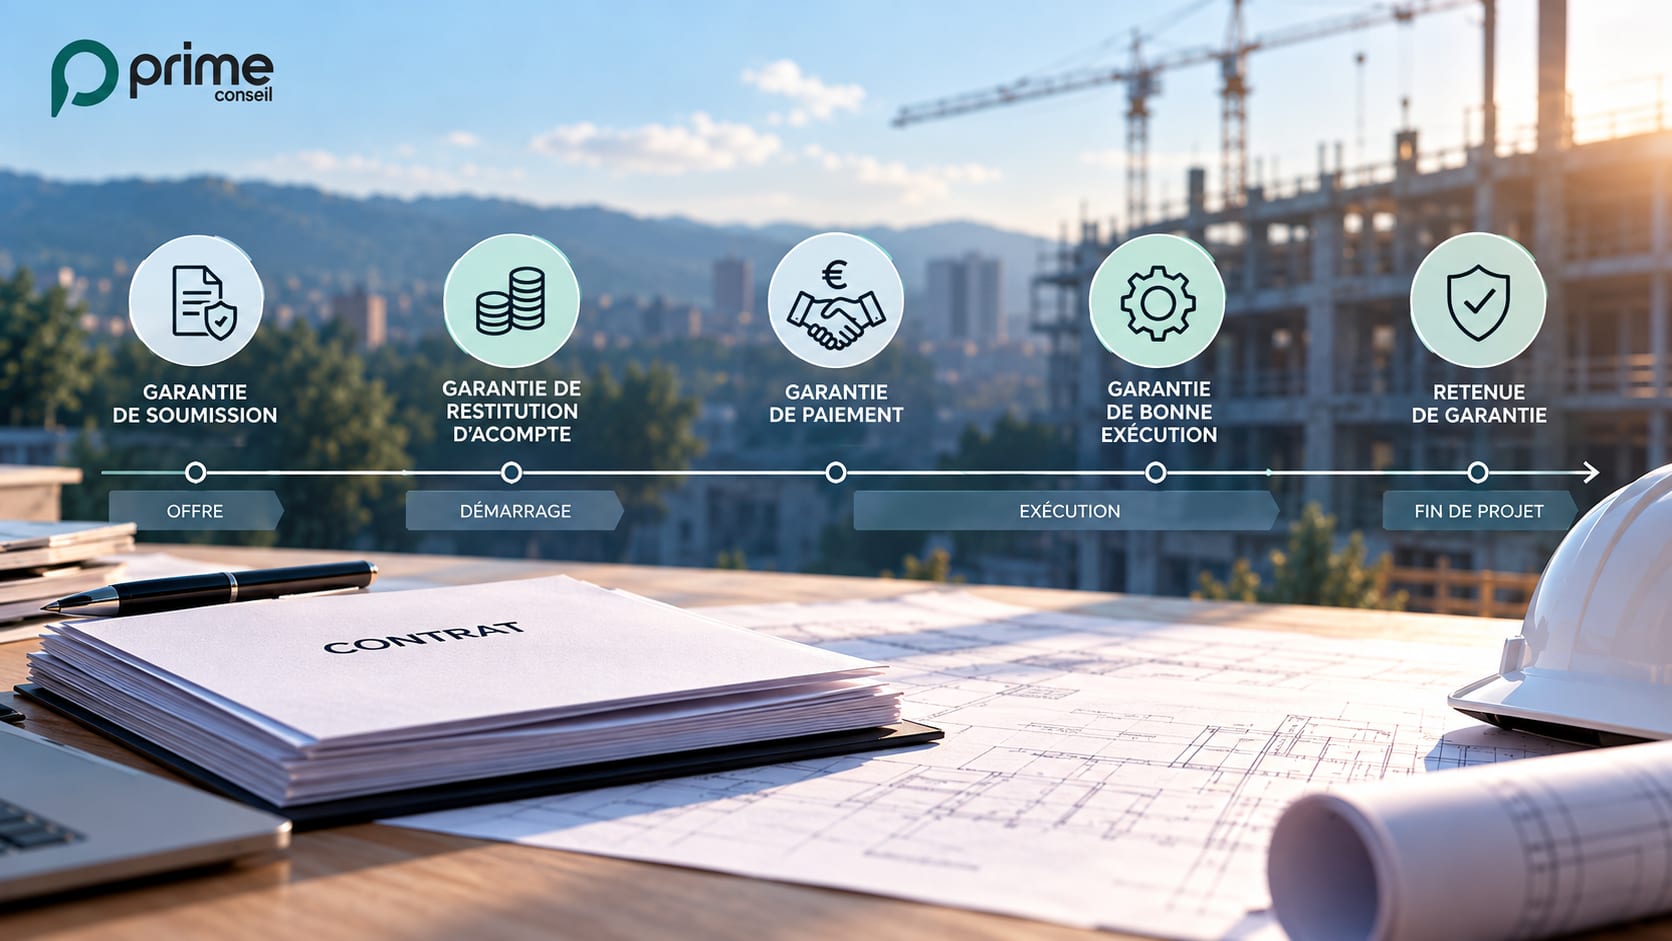
This article provides an overview of the main guarantees a contract manager is likely to encounter during a project, presented in the order they appear, from submission of the tender to the end of the guarantee period.
What is the purpose of a guarantee in a project?
A guarantee answers a simple question: what happens if the other party fails to do what it promised? It allows a client to pay an advance without fear of losing it, a supplier to be paid without depending solely on its client's financial health, and a project owner to have snags cleared without having to pursue a defaulting contractor. In other words, it makes possible commitments that no one would otherwise take on.
Two things are worth distinguishing from the outset, because they are regularly confused in contracts and in conversation. The subject of the guarantee is what it covers: an advance payment, performance, the clearing of snags. The instrument is the legal form that carries it: an on-demand guarantee, a surety bond, a letter of credit, and so on. The same subject can be covered by very different instruments, and it is the instrument that determines what happens on the day someone tries to use it. We will come back to this.
At tender stage: the bid bond
The first guarantee generally encountered on a project precedes the contract itself. This is the bid bond, which assures the client that the tender submitted is genuine and that the successful bidder will sign the contract on the terms proposed. Its amount is modest, and it ends when the contract is signed (or when the bidder is eliminated).
In France, it remains uncommon in public procurement contracts, whereas in other parts of the world it is a mandatory step. In India and several Asian countries, the bid bond or its banking equivalent simply determines whether a tender is admissible in public procurement. For a company bidding internationally, the ability to mobilise this guarantee quickly is one of the prerequisites of a response, on a par with references or financial capacity, which is one more reason to involve the contract manager from the tender stage.
At the start: advance payment, performance, and the guarantee owed by the project owner
The start of a contract concentrates the most structurally important guarantees. First, the advance payment guarantee is the natural counterpart to the advance paid by the client. It covers the repayment of sums paid before any work is carried out, and its amount matches that of the advance, often 10 to 20% of the contract on large projects. Two points are regularly subject to negotiation: when it comes into effect, which the supplier should ideally tie to the funds actually being received in its account, and its reduction profile, which normally follows the amortisation of the advance across successive payment applications. An advance payment guarantee that does not decrease ties up bank facilities unnecessarily for months.
Next, the performance bond protects the client against non-performance or poor performance of the contract. It most often represents 5 to 10% of the contract value and runs for the whole duration of performance, sometimes beyond, until the end of the guarantee period. In FIDIC contracts, clause 4.2 makes it an obligation for the contractor to provide within 28 days of the letter of acceptance, with clearly defined grounds for calling it. It is the guarantee most often talked about, and the one whose call causes the most damage.
Finally, there is a guarantee that is often overlooked because it runs the other way. In private construction contracts, the project owner must also guarantee payment to the contractor. Article 1799-1 of the French Civil Code makes this compulsory above a certain threshold, either through direct payment by the lender where the works are financed by credit, or through a joint and several surety provided by a financial institution. Many construction companies do not ask for it at the contract negotiation stage, either through lack of awareness or for fear of upsetting the client. Yet it is a right (one that many companies claim only once the contract has been signed), and on a project that goes wrong, it is often the only real protection against non-payment.
At the end of performance: retention and the guarantee period
As the project approaches completion, a different family of guarantees takes over, focused on the quality of what has been delivered.
Retention consists of the client holding back a portion of the sums due, until snags are cleared and/or the guarantee period has expired. In public procurement, it is capped at 5% of the contract and must be repaid within thirty days of the guarantee period expiring. In private construction contracts, the law of 16 July 1971 strictly regulates the mechanism: a maximum of 5%, an obligation to deposit the sums with a third party, and the option for the company to replace it with a surety bond. This last point matters for cash flow: rather than letting 5% of its turnover sit idle for a year, the company can substitute a guarantee exempting it from retention, and cash in its payment applications in full.
Guarantees on the supplier's side
Everything above is largely geared towards protecting the client. The supplier also has instruments available. The payment guarantee covers the price of the services and is negotiated whenever the client's solvency or the country of performance presents a risk. The documentary letter of credit remains the reference tool for exports, securing payments as work progresses. The parent company guarantee commits the group's parent company where the contracting subsidiary does not offer sufficient financial standing.
Guarantee instruments
Let us return to the distinction made at the start. Three main families of instruments carry the guarantees described above, and they are not equivalent:
First, the on-demand guarantee, or autonomous guarantee, detached from the main contract. The guarantor pays on simple demand from the beneficiary, without being able to challenge the merits of the call or raise defences drawn from the contract. It is the dominant instrument internationally, governed by the URDG 758 rules, and the one required by most FIDIC templates and public buyers. Its strength for the beneficiary is also its risk for the principal: an abusive call is contested after payment, rarely before.
The surety bond, by contrast, is accessory to the contract. The guarantor can raise anything the principal debtor could raise itself: compliant performance, disputing the amount, set-off. It protects the beneficiary less, but it protects the party providing it more.
Between the two, there are conditioned forms: documentary guarantees whose call requires the production of specific documents, guarantees whose entry into force or reduction is tied to verifiable events, and standby letters of credit internationally. Contract vocabulary is misleading here, and an "on-demand surety bond" can refer to either one, depending on the wording. Only reading the guarantee instrument itself tells you what you actually hold.
The contract manager's role
Admittedly, the contract manager does not draft or issue guarantees. However, they are often the only person on the project who sees the schedule, the payments and the contract wording all at once, the three elements on which the life of a guarantee depends.
Keeping a register of guarantees in force, ideally starting with the contract memo, with their amounts, validity dates and reduction conditions, aligning these dates with a schedule that slips, triggering releases as soon as conditions are met, preparing or responding to a call: this management is rarely assigned explicitly to anyone, and it naturally falls to whoever holds the contract.
There is also a more strategic dimension. Guarantees consume bank facilities, and a company that accumulates bid bonds, advance payment guarantees and performance bonds across a dozen projects may find itself unable to respond to the next tender. Negotiating a reduction against a milestone, often as part of a contract amendment, substituting a surety bond for retention, securing the release of a forgotten guarantee: these are direct cash flow gains, within the contract manager's reach, requiring only a little attention.
In short, a guarantee is a standard tool, a commodity in the world of projects. Be careful though, as it can become a source of difficulty and extra costs when no one is watching it.